'Q2 2026 Estimated Tax Deadline for Freelancers: How to Calculate and Pay by
Q2 2026 Estimated Tax Deadline for Freelancers: How to Calculate and Pay by June 16
The April 15 deadline just passed. If you paid your Q1 estimate, good. The Q2 2026 estimated tax deadline for freelancers is June 16 on many calendars used in freelancer guides, and you have a short window after Q1 to calculate and send it.
Q2 covers only two months of income, April 1 through May 31, but lands soon after Q1. 2026 also includes newer above-the-line deductions under the One Big Beautiful Bill Act (OBBBA). Those rules can change what you owe. This post is education, not tax advice. Confirm your payment with a CPA.
Why do some calendars show June 16 instead of June 15?
The IRS sets estimated tax payments on the 15th of the due month. When a due date falls on a Saturday, Sunday, or legal holiday, the IRS estimated tax page says the payment is on time on the next business day.
Many freelancer guides list June 16, 2026 as the Q2 date based on that weekend rule. Miss a required installment and underpayment penalty interest can start for that period. The underpayment rate is the federal short-term rate plus 3 percentage points. IRS quarterly tables have shown a 7% individual underpayment rate for parts of 2026.
Example: on a missed Q2 payment of $5,000, rough interest over about ten months at 7% annually is on the order of a few hundred dollars. There is no informal grace period. For the full year, common 2026 estimated tax dates listed for freelancers are April 15, June 16, September 15, and January 15, 2027.
What period does Q2 actually cover?
Q2 covers income earned April 1 through May 31. Two months, not three. Q1 covered January through March. Q3 picks up June through August.
The compressed structure matters because you have less time to accumulate cash for the payment, especially if May is a strong revenue month. Many freelancers learn this the first year they pay estimates.
The IRS does not require your check to equal exactly two months of income. The IRS cares whether you have paid enough in total by each deadline to avoid underpayment penalties. Two safe harbor methods define "enough."
Safe harbor method 1: 100% of last year's tax. Take your total 2025 federal tax liability from your Form 1040 and divide by four. Pay that amount each quarter. If your 2025 adjusted gross income exceeded $150,000, the prior-year safe harbor is generally 110% of last year's tax, not 100%.
Safe harbor method 2: 90% of this year's estimated tax. Project what you expect to owe for all of 2026, multiply by 90%, and divide by four. This helps if 2026 income is tracking lower than 2025.
You only need to meet one method. Most freelancers use method 1 because it needs no projection.
Which 2026 numbers change the estimate?
OBBBA changes affect 2025 and 2026 filings. The items below are the ones freelancers most often ask about when projecting estimates.
Standard deduction
For 2026, the IRS lists the standard deduction as $16,100 for single filers and $32,200 for married filing jointly. That is up from $15,750 and $31,500 in 2025.
When you project 2026 taxable income under method 2, start with gross income minus the standard deduction if you do not itemize.
Above-the-line deductions on Schedule 1-A
Schedule 1-A consolidates newer deductions that can reduce adjusted gross income. IRS Working Families Tax Cuts guidance describes the main worker deductions.
No tax on tips: up to $25,000. Workers in occupations the IRS identified as customarily receiving tips may deduct qualified tips up to $25,000, with MAGI phase-outs beginning above $150,000 ($300,000 joint). Tips must be voluntary customer tips and reported on a W-2, 1099, other statement, or Form 4137. Ask a CPA whether your work category qualifies.
No tax on overtime: up to $12,500 single, $25,000 MFJ. The deduction targets the premium portion of qualifying overtime (the "half" of time-and-a-half) for pay that meets FLSA rules and reporting rules. MAGI phase-outs begin above $150,000 ($300,000 joint). Many pure freelancers will not qualify. Confirm with a CPA.
Auto loan interest: up to $10,000. Interest on a qualifying personal-use vehicle loan may be deductible up to $10,000. IRS guidance requires a loan originated after December 31, 2024, a vehicle whose original use begins with you, final assembly in the United States, and other limits. Phase-outs begin above $100,000 MAGI for single filers and $200,000 for joint filers. The deduction is fully eliminated at $150,000 MAGI for single filers under the Schedule 1-A phase-out math.
These deductions matter for estimates because they can shrink the taxable base you project. Example: a freelancer with $90,000 in gross self-employment income, qualifying tips of $15,000, and $6,500 in qualifying auto loan interest is working with a smaller tax base than under older rules, if a CPA confirms eligibility.
How do you calculate a Q2 payment step by step?
Here is one framework freelancers use. Confirm every deduction with a CPA before you rely on it.
- Project annual net self-employment income. Take year-to-date net income through May 31, divide by months elapsed, and multiply by 12. Or use signed contracts if income is lumpy.
- Apply the self-employment tax calculation. Self-employed people pay 15.3% SE tax (12.4% Social Security + 2.9% Medicare). SE tax is figured on 92.35% of net SE income. You may deduct the employer-equivalent half of SE tax above the line. For 2026, Social Security applies only to the first $184,500 of covered earnings.
- Subtract the standard deduction and any Schedule 1-A amounts your CPA confirms. Single filers start with the $16,100 standard deduction before other adjustments.
- Apply 2026 income tax brackets. Federal rates remain 10%, 12%, 22%, 24%, 32%, 35%, and 37%. For a single filer in 2026, IRS tables put 10% on the first $12,400 of taxable income, 12% through $50,400, and 22% through $105,700.
- Add income tax and SE tax, then subtract credits. Divide by four for equal installments, or use the annualized income method on Form 2210 Schedule AI if income is lumpy.
- Check against prior-year safe harbor. If your current-year estimate is lower, many freelancers still pay at least the safe harbor amount to stay penalty-free.
Example: a single freelance designer with $85,000 projected net income and no Schedule 1-A deductions. SE tax on $78,498 (92.35% of $85,000) = about $12,010. Deductible half = about $6,005. Adjusted income = $85,000 minus $6,005 minus $16,100 = $62,895 taxable. Estimated income tax on $62,895 is roughly $9,400 in this sketch. Total annual tax sketch = $9,400 + $12,010 = $21,410. Divided by 4 = about $5,353 per quarter before credits.
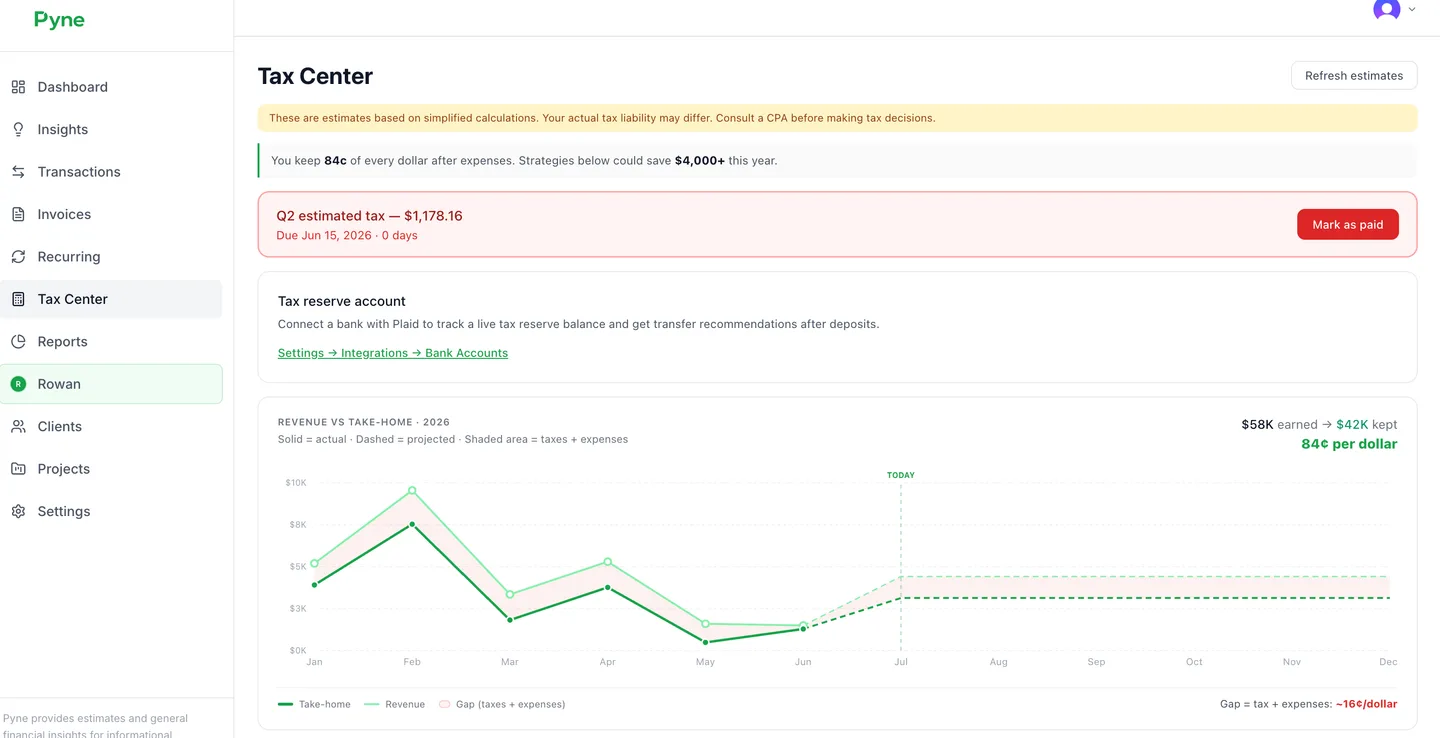
Tools like Pyne can keep the income side organized; see Pyne pricing. A spreadsheet works too. Rowan, Pyne's AI financial copilot, helps you track what came in. A CPA still owns the filing decision.
Why does the 1099-NEC threshold change matter for estimates?
For payments made in 2026, the 1099-NEC reporting threshold is $2,000 (up from $600 for earlier years). Clients paying you between $600 and $1,999 in 2026 may not issue a 1099-NEC.
The income is still fully taxable. You must report business income whether or not a form arrives. Track invoices and bank deposits for Q2 and Q3 estimates. Do not wait for January 1099s to discover what you earned.
How should you think about IRS enforcement and accuracy?
Self-employed underreporting has long been a large part of the individual tax gap. Paying estimates from real books reduces avoidable risk. Clean records and timely estimates leave less to explain later.
Pay by the Q2 date on your calendar. Use actual income numbers. Apply only the OBBBA deductions your CPA confirms.
How do you pay the estimate?
Common IRS payment options:
- IRS Direct Pay at IRS.gov: free, no account required, bank transfer. Specify tax year 2026 and the correct estimated-tax period.
- EFTPS: schedule the payment in advance.
- Check or money order with Form 1040-ES: payable to "United States Treasury," with your SSN and "2026 Form 1040-ES" in the memo. Allow mailing time.
State estimated payments are separate when your state requires them. Do not assume your state matches the federal date.
What is the one action before the Q2 date?
Open your books. Tally April and May revenue. Look at projected annual income. Confirm any Schedule 1-A deductions with a CPA. Calculate and send the payment before the Q2 deadline you are using.
Newer deductions can reduce what some freelancers owe. They only help if you run the numbers with eligible facts.
Sources
<!-- TAX_FLAG: post=q2-2026-estimated-tax-deadline-freelancers; current="Post states June 15, 2026 falls on a Sunday so Q2 moves to June 16"; source="calendar check: June 15, 2026 is Monday, so the statutory June 15 due date does not shift under the weekend rule on IRS estimated taxes page"; url=https://www.irs.gov/businesses/small-businesses-self-employed/estimated-taxes --> <!-- TAX_FLAG: post=q2-2026-estimated-tax-deadline-freelancers; current="Auto loan interest: purchased a new passenger vehicle assembled in the United States after December 31, 2024 (as previously phrased in source draft)"; source="IRS Working Families page: loan originated after Dec. 31, 2024; original use begins with taxpayer; final assembly in the United States (date attaches to loan origin, not assembly date)"; url=https://www.irs.gov/newsroom/working-families-tax-cuts-individuals-and-workers --> <!-- TAX_FLAG: post=q2-2026-estimated-tax-deadline-freelancers; current="IRS AI enforcement section previously cited GAO '126 active AI use cases' and related operational claims"; source="could not independently verify the GAO count as a primary citation in this edit pass; section shortened to avoid unverified operational statistics"; url= -->Related
Pyne provides estimates and general financial insights for informational purposes only. This is not tax, legal, or financial advice.